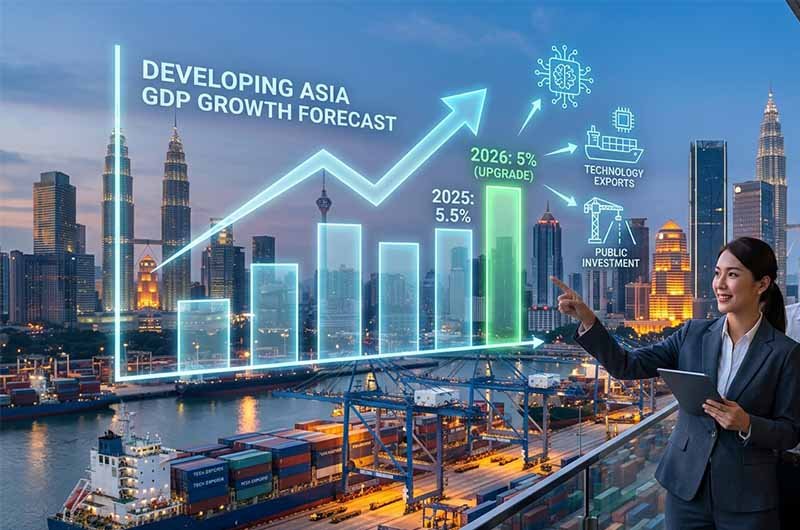
Economic expansion across developing Asia and the Pacific is projected to moderate to 5% in 2026 from 5.5% in 2025, before nudging up slightly to 5.1% in 2027, according to the Asian Development Bank’s (ADB) Asian Development Outlook (ADO) September 2026 report.
The ADB upgraded its regional growth projection for 2026 by 0.1 percentage points compared to its July estimate, citing stronger-than-expected economic performance across key parts of the region. Regional resilience continues to be underpinned by solid investment, targeted government stimulus, and robust technology exports linked to the global artificial intelligence (AI) boom.
Inflation Outlook
- 2026 Forecast: Revised down to 4.2% (from 4.3%), as price stabilization efforts help absorb sustained energy market pressures.
- 2027 Forecast: Adjusted slightly upward to 3.5% (from 3.4%).
- Both figures remain above the 3% inflation rate recorded in 2025.
ADB President Masato Kanda emphasized that while the region remains resilient, downside risks are compounding. Key threats include escalating global conflicts—such as potential spillovers from the Middle East and the Russia-Ukraine war—alongside a strengthening El Niño pattern through early 2027 that could disrupt agricultural output and hydropower generation, driving up food and energy costs. The bank also warned of potential risks from AI stock valuation corrections, tightening financial conditions, and trade policy uncertainty.
Regional Breakdown
| Subregion | 2026 Growth Forecast | 2027 Growth Forecast | Key Drivers / Notes |
| South Asia | 6.4% (up from 6.0%) | 6.5% (down from 6.7%) | Upgraded for 2026 due to strong public investment and exports in India. 2027 trimmed due to trade and weather headwinds in India, Bangladesh, Nepal, and Afghanistan. |
| Southeast Asia | 4.7% (up from 4.6%) | 4.9% (up from 4.8%) | Upgraded across both years following strong first-half performance in 2026. |
| East Asia | Unchanged | Unchanged | Outlook remains steady, including projections for the People’s Republic of China. |
| Caucasus & Central Asia | 3.7% (down from 3.8%) | 4.1% (down from 4.2%) | Softened slightly due to weaker external demand, particularly in Türkiye. |
| Pacific | 3.0% (down from 3.3%) | 2.9% (down from 3.2%) | Sharpest cuts owing to energy market disruptions and El Niño impacts on mining and agriculture. |