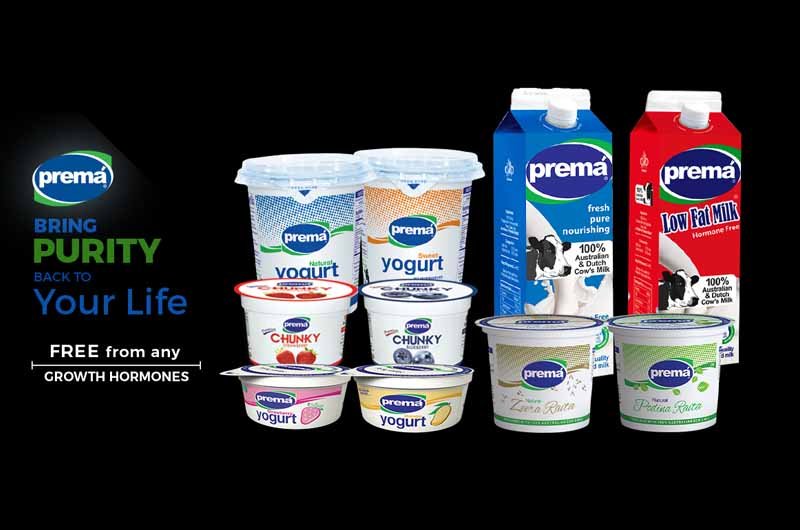
At-Tahur Limited, a prominent player in Pakistan’s dairy sector known for its ‘prema’ brand, announced its un-audited consolidated financial results for the first quarter ended September 30, 2026. While the company recorded healthy topline growth, inflationary pressures and soaring finance costs resulted in a significant decline in net profitability.
According to the financial statements released to the Pakistan Stock Exchange, the company’s core revenue from contracts with customers surged by 11.6% to Rs. 1.73 billion during the quarter under review, compared to Rs. 1.55 billion in the same period last year.
Including the gains arising from the initial recognition of milk and changes in the fair value of dairy livestock, the total recognized income expanded to nearly Rs. 3 billion, indicating continued growth in biological assets and milk production.
Operational Pressures and Rising Finance Costs
Despite the robust growth in sales, At-Tahur’s bottom line came under immense pressure due to escalating input costs. Operating costs rose noticeably to Rs. 2.24 billion, neutralizing much of the revenue gains. Furthermore, administrative, selling, and other operating expenses all witnessed an uptick compared to the previous year.
The most significant drag on profitability, however, came from the finance cost component. Reflecting a high-interest rate environment, the company’s finance costs jumped by over 51% to Rs. 76.68 million, compared to Rs. 50.71 million in the corresponding quarter of 2025.
Profitability Declines
Consequently, At-Tahur Limited reported a Consolidated Profit After Taxation of Rs. 31.47 million for Q1 2026, marking a decrease of approximately 26.6% compared to a profit of Rs. 42.87 million in Q1 2025.
This decline in net profit translated to reduced returns for shareholders. The company’s Earnings Per Share (EPS) dropped to Rs. 0.14, down from Rs. 0.20 in the same quarter last year.
Financial Position and Cash Flow
As of September 30, 2026, At-Tahur’s total assets stood at Rs. 10.4 billion, largely composed of biological assets valued at Rs. 4.7 billion and property, plant, and equipment worth Rs. 2.1 billion. Total equity remained stable at Rs. 6.94 billion.
The cash flow statement revealed a challenging quarter for liquidity. The net cash flow generated from operating activities turned negative to the tune of Rs. 138.6 million, largely due to finance costs paid and taxes. To manage liquidity, the company liquidated a substantial portion of its short-term investments, reducing them from Rs. 248 million in June 2026 to just Rs. 32 million in September 2026.
Despite the quarterly profit dip, At-Tahur maintains a strong overall financial position with substantial asset backing, though managing working capital and finance costs will remain critical in the immediate future.